Stablecoin Payments in Asia: Inside the Products
Grab turns digital currency into wallet spending. Nium connects USDC balances to fiat payouts. SCB puts stablecoins between settlement partners. Their disclosures point to three different payment businesses.
Originally published by Panasia Research.
- Topic
- Stablecoin payments
- Published
- 2026-09-11
- Reading
- 23 min
- Sections
- 16
- References
- 16
 IUM LABSResearch
Cover artwork and image sources
- Cover: AI-generated editorial illustration · ium Labs Research.
- Three Grab app screens from Triple-A’s case study: the top-up method list with Digital Payment Tokens, an SGD 150 amount entry with USDC selected, and the completed top-up details. · Triple-A case study
Key takeaways
- 01
A stablecoin transfer is one step in a payment. The customer outcome depends on the funding and payout institutions around it.
- 02
Payout funding, wallet top-ups and remittance settlement address different business problems and require different evidence.
- 03
Lower prefunding does not by itself make a payment cheaper. Conversion, payout and operating costs belong in the same calculation.
- 04
At a 5% annual funding rate, releasing a full payment balance two days earlier is worth 2.74 basis points. On our arithmetic, a route that costs 10 bp more needs about 7.3 days of full release to break even.
- 05
An audience is not usage. The 18 million Coins.ph users named in its 2023 USDC partnership with Circle describe a platform audience, not people observed sending USDC remittances.
- 06
For Korea, ten digital asset and stablecoin bills were still pending in July 2026, and the FSC’s September roadmap ties stablecoin-linked payments to that pending law. A Korea plan should not yet depend on a won stablecoin leg.
One payment story. Three different businesses.
Stablecoins can fund a wallet, connect a company’s token balance to fiat payouts, or sit between settlement partners. Start with the product people use: the same technology changes a different part of the business in each case.
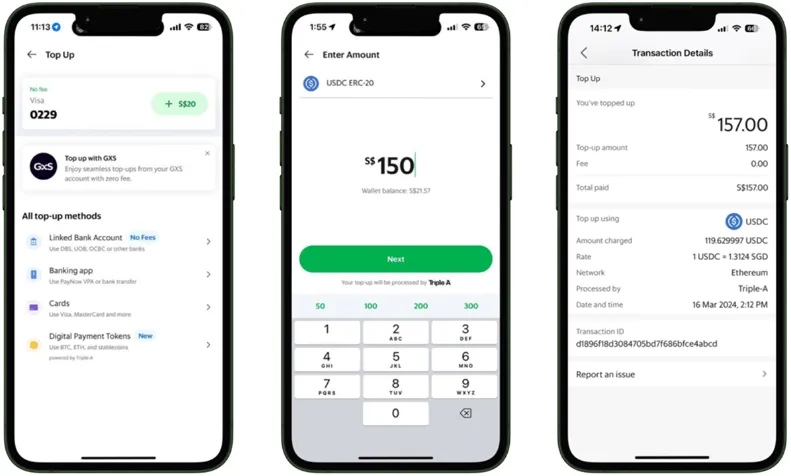
A token balance becomes an everyday purchase.
A familiar wallet is the starting point. The user is funding spending inside Grab; the product does not require the everyday purchase to end in cryptocurrency.
- Choose digital payment tokens as the top-up method.
- Enter the top-up amount in SGD and confirm from a crypto wallet.
- The wallet shows the completed top-up in SGD.
Source: Triple-A’s Grab case study.
Triple-A describes digital-currency funding for a familiar wallet. Its account says Grab receives SGD and that settlement to Grab’s bank account follows the day after the transaction. The supported assets include BTC and ETH as well as the stablecoins USDC and USDT.
Where to look for value. Access to a customer’s existing balance. A faster token leg does not establish faster merchant bank settlement, or a stablecoin-specific growth effect.
The customer already has USDC.
Nium’s USDC funding launch connects an existing token balance to its fiat payout network. Read the announcement.
Nium’s August 27, 2026 release describes eligible corporate clients funding an account with USDC, which is converted to USD and credited automatically, then paid out in fiat through its network. The launch connects an existing token balance to ordinary business payments.
Where to look for value. The separate conversion workflow the business would otherwise use. This is a different comparison from a company starting with fiat deposits.
Grab’s top-up starts with a consumer who wants to spend. Nium’s funding proposition starts with a business that already holds USDC and needs to pay in fiat. Removing a separate conversion-and-funding step is the opportunity; the release alone does not establish a lower total price.
Conversion and access conditions still matter. Nium’s terms put screening and partner cut-off times between token receipt and usable fiat credit.
The token sits between institutions.
SCB moves the comparison behind the customer interface. Here the proposed value sits in how institutions settle with one another, rather than in a new consumer top-up or corporate funding option.
SCB’s October 2024 announcement, as The Block reported it, describes a “fully commercialized” stablecoin settlement service that removes the need for prefunding between partners. The customer-facing transaction can remain in local currency.
Where to look for value. Balances and operating work inside the settlement chain. None of the reports we read quantifies realized savings.
These are distinct products, not a provider ranking. The study below also examines Coins.ph / Circle, tokenized deposits and programmable vouchers.
The business changes with the starting balance.
Our reading of these cases: the commercial question is which existing balance a product can connect to a useful destination. The token is part of that connection; it does not define the whole business.
For Grab, that destination is a familiar consumer wallet. For Nium, it is fiat payouts from a company’s existing USDC balance. For SCB and Lightnet, the change sits between settlement partners. Those differences determine the customer, the integration and the evidence a business needs before expanding.
This gives Asia-facing teams a more specific starting point than a general “stablecoin payments” proposition. Identify the customer’s existing balance and desired endpoint, then explain the particular step the product makes easier. A wallet top-up, a corporate payout and bank settlement need different distribution and institutional relationships. Our Asia Market Entry Decision Framework scopes a first market brief around the same funding, conversion and bank-delivery roles.
The disclosures establish product workflows. They do not establish a matched, independently measured cost advantage across these businesses. Adoption, realized savings and reliable delivery each need their own evidence. The analysis below sets out how we would test those claims.
From USDC funding to usable fiat.
The shortcut still has a cash gate.
The launch describes automatic USD crediting. The August 11, 2026 Pay In terms add the operating conditions: a digital asset partner receives, custodies, screens and converts the assets, and fiat credit is subject to the partner’s cut-off times. Fees and conversion mechanics are notified through the platform. The terms also allow Nium or the partner to reject, delay, freeze or return the asset.
The product page states that USDC funding and payouts are not available in Hong Kong. Its network reach does not establish eligibility for every Asian company or corridor.
Our interpretation. The potentially valuable shortcut is removing a separate conversion-and-funding handoff. Whether that lowers cost or time remains a quote-and-execution question. Measure usable fiat credit and beneficiary receipt, not just token arrival.
| Route A: separate conversion | Route B: direct funding | |
|---|---|---|
| Same starting point | One eligible company’s existing USDC balance | One eligible company’s existing USDC balance |
| Path | USDC → eligible conversion provider → company bank funds → fiat payout | USDC → Nium’s conversion partner → USD available balance → fiat payout |
| Same finish line | Same net local-currency amount in the same supplier account, by the same deadline | Same net local-currency amount in the same supplier account, by the same deadline |
Hold customer entity, destination, amount, quotation time and payment purpose constant. Obtain eligibility confirmation for both routes before collecting prices. A business starting with fiat needs a separate comparison that includes buying USDC.
A published price is only one leg.
Circle’s own redemption pricing illustrates why “redeem at par” is not enough to price Route A. When Circle changed its fees in 2024, Cointelegraph, citing Bloomberg, reported fees on daily redemptions of at least $2 million, starting at 0.03% per transaction and rising to as much as 0.1% above $15 million. Redeeming without fees meant waiting up to two days for the cash. Circle publishes its current tiers on a help page that we could not open in a dated form, so we quote none of its 2026 figures. Tier terms are not an end-to-end payout quote.
What changes the comparison. Verify account eligibility, actual tier, aggregate daily and monthly flows, banking charges and the final FX/payout quote. Do not turn a processing window of up to two days into two calendar days of measured funding savings.
The disclosed payment paths.
Grab / Triple-A
- Digital currency: customer top-up
- SGD wallet: conversion by Triple-A
- Bank settlement: next day, per the case study
Nium
- USDC balance: corporate starting funds
- USD credit: conversion into the account
- Fiat payout: existing payout network
SCB / Lightnet
- Local currency: customer transaction
- Stablecoin: settlement between partners
- Local currency: customer endpoint
These paths summarize provider disclosures and press reports of them, not live transaction traces.
Two days saved. Only 2.74 basis points to spend.
At a 5% annual funding rate, releasing an entire payment balance two calendar days earlier is worth 2.74 basis points. Any greater net increase in route costs needs another source of savings. That is a hurdle to test, not a provider performance claim.
$7.26: the further avoided cost needed to break even on a $10,000 payment when the new route costs 10 bp more (Source: ium Labs calculation)
ium Labs calculation, not observed savings. Assumes the entire $10,000 balance is released for two days: $10,000 × 5% × 2 ÷ 365. The extra 10 bp cost is hypothetical, not a quoted provider fee.
Capital release alone does not pay for this example. At these assumptions, a 10 bp cost increase needs 7.3 calendar days of full-balance release to break even. If only half the balance is freed, the two-day benefit falls to 1.37 bp. A larger payment increases the dollar benefit, but not the basis-point budget unless pricing or the funding profile also changes.
How much can faster funding pay for?
| Calendar days saved | 3% rate | 5% rate | 10% rate |
|---|---|---|---|
| 1 day | 0.82 | 1.37 | 2.74 |
| 2 days | 1.64 | 2.74 | 5.48 |
| 5 days | 4.11 | 6.85 | 13.70 |
| 10 days | 8.22 | 13.70 | 27.40 |
ium Labs sensitivity calculation: annual funding rate × calendar days saved ÷ 365 × released share × 10,000. Rates and durations are illustrative, not market estimates. Use the payer’s incremental funding cost or foregone yield, without counting both. A provider’s lower prefunding is not a payer saving unless passed through.
Timing starts when funds cease to be usable and ends when equivalent funds become usable again. A faster blockchain confirmation alone does not establish a shorter funding period. FX movements, credit and custody losses are outside this simple model; a positive result is not an approval to transact.
Our companion paper on tokenized money funds applies the same released-capital test to treasury cash, with the same conclusion: a fee needs days of productive money to pay for it.
Testing a corporate payout route.
For a business starting with USDC, compare direct funding with a separate conversion and fiat-funding route. Hold the customer, destination and required net recipient amount constant.
The evidence that would change that verdict
Collect simultaneous quotes for the same recipient amount, record all deductions, and timestamp both usable funding and beneficiary receipt. Repeat across ordinary days, cut-offs and exceptions; one successful transfer is not a reliability estimate. Record failed or returned payments as well as successful ones.
Choose a route only after the matched cost difference, actual funding benefit and operating burden are understood. A cheaper quote that misses the supplier’s deadline has not met the same requirement.
Go deeper into the evidence.
The rest of this article is the underlying working paper on six programs. The calculations are ium Labs scenarios. We have not executed matched transfers, obtained customer-specific quotes, interviewed the operators or completed independent peer review.
Abstract
A stablecoin transfer and a completed customer payment are different units of analysis. This paper compares four stablecoin-related payment programs with Asian connections, alongside two boundary cases: tokenized bank deposits and programmable vouchers. The public record describes bank remittance settlement, corporate payout funding, consumer wallet top-ups and a remittance education partnership. Those activities have different customers, cash flows and evidentiary maturity. The central finding is a classification rather than an adoption estimate: the role of the token in the payment chain determines which business problem is being addressed and which institution must complete the customer outcome. A second contribution is a transparent break-even model showing why savings in prefunding may be outweighed by conversion and operating costs. The analysis supports measuring beneficiary availability, exception resolution and total workflow cost. It does not establish industry-wide savings, current corridor availability or the superiority of stablecoins over bank deposits. All case claims are attributed to primary disclosures or to press reports of them, and illustrative calculations are separated from observed evidence.
Research question
The phrase “stablecoin payments” can describe several different things: a customer spending an existing token balance, a provider moving settlement funds between institutions, or a platform accepting tokens before paying a beneficiary in local currency. Those arrangements can produce similar promotional language while solving different problems. This paper asks: where does the token enter and leave the payment workflow, and what does that imply for the customer, commercial partner and measurement of success?
The question matters to a blockchain company preparing an Asian expansion. Selling wallet acceptance to a consumer platform is a different assignment from connecting a bank's settlement operation or funding a corporate payout account. The relevant counterparties, integration burden and evidence of value differ. Treating them as one market can lead a team to cite a successful consumer application as evidence for an unrelated enterprise proposition.
Our contribution is a case-based classification of these roles, coupled with an explicit economic test. We examine what each program's source establishes, identify the residual fiat or bank dependency, and describe the observations needed to evaluate a business result. This is a study of publicly documented arrangements. It is not a census of stablecoin adoption, a remittance price survey or a recommendation to use a particular product.
Case selection and definitions
The corpus contains four stablecoin-related programs: SCB / Lightnet, Nium USDC funding, Grab / Triple-A and Coins.ph / Circle. The DBS / OCBC / UOB interbank program is included as a tokenized-deposit comparator; Circle / Grab's voucher pilot is included to test the boundary between programmable digital experiences and settlement money. These are six programs, not six independent companies. The two Grab arrangements involve different partners and functions and are not treated as one deployment.
Selection was purposive. A case needed an identifiable payment workflow or explicitly described commercial objective, an Asian institutional or customer connection, and a primary document or, for SCB, press reports of one. Dates range from September 2023 to September 2026, with an undated provider case study reviewed on 11 September 2026. Nium is a global provider also participating in a separate Singapore pilot with Visa under BLOOM, an initiative the Monetary Authority of Singapore (MAS) launched on October 16, 2025 to “enable settlement in tokenised bank liabilities and well-regulated stablecoins.” The Visa pilot explores whether settlement can “occur seven days a week.” That connection motivates inclusion; it is not evidence that its USDC funding product is available to every Asian customer, or that the two programs are identical. Its USDC funding release is dated August 27, 2026.
Each case was coded for token role, customer-facing value, conversion boundary, disclosed stage and missing outcome data. “Provider-reported availability” means that the source describes the service as available. “Reported use” requires a described customer use or operating result. “Pilot” and “announced collaboration” remain distinct. These labels classify documents; they do not certify products or imply that a program has not progressed beyond the selected source.
A stablecoin is considered here as a token designed to maintain a reference value. A tokenized deposit represents a bank-deposit relationship in token form. A voucher expresses a right or condition of use and should not automatically be treated as a broadly usable settlement asset. The BIS’s June 2026 Annual Economic Report chapter on money ties the prospects of tokenized money to whether it can “preserve singleness through credible redeemability in central bank money at par,” and finds that current stablecoin designs “fall short on foundational properties of money.” That is a system-level critique, not a measured verdict on the six programs examined here.
Case evidence
SCB / Lightnet: a settlement rail behind local-currency transactions
SCB’s October 2024 announcement, as reported by The Block, Ledger Insights and Fintech News Singapore, describes stablecoins used for cross-border settlement with Lightnet, with custody technology from Fireblocks. Ledger Insights reports that the project graduated from the Bank of Thailand regulatory sandbox in October 2024; The Block quotes the bank calling the service “fully commercialized.” The reports describe customers transacting in local currencies and the removal of “the need for pre-funding between partners.” Fintech News Singapore reports that SCB and Lightnet plan to roll the service out for corporate clients. None of the reports quantifies realized savings or identifies a complete set of live corridors and transaction conditions.
Interpretation. The customer does not necessarily need to become a long-term stablecoin holder for the settlement arrangement to be useful. The proposed benefit sits inside an institutional payment chain. An outside supplier should therefore identify the settlement, liquidity or reconciliation function it could improve, rather than assume the opportunity is primarily consumer wallet acquisition.
Nium: existing USDC balances become payout funding
Nium’s August 27, 2026 release describes eligible corporate clients funding an account with USDC, conversion to USD, and payout through its existing fiat network. Existing clients are told there is “no new integration.” The advertised reach of more than 190 countries describes the provider’s network; the release is not a corridor-by-corridor eligibility or settlement-time specification. It announces availability, but gives no transaction cohort or realized working-capital result.
Interpretation. This arrangement starts with a business that already has tokens. That is materially different from a business that must first buy them with fiat. The avoided workflow may be a separate manual off-ramp, rather than every cost in a conventional cross-border transfer. A sales proposition should specify the starting balance and required endpoint before claiming a saving.
Grab / Triple-A: token funding, familiar wallet use
Triple-A’s case study describes Grab wallet top-ups using USDC, USDT, BTC and ETH, with conversion handled by Triple-A. It states that Grab receives SGD amounts and that settlement to Grab’s bank account occurs the day after the transaction. The provider reports top-up volume doubling in six months, but supplies neither an absolute base nor a controlled comparison. BTC and ETH are not stablecoins, and the study does not isolate their contribution from stablecoin activity.
Interpretation. This is a consumer funding option connected to an existing application. It demonstrates why a fast blockchain leg should not be equated with immediate merchant bank settlement. It also shows the measurement problem in claims of customer growth: payment volume may rise without establishing incremental customers, a lower acquisition cost or a stablecoin-specific causal effect.
Coins.ph / Circle: an acquisition proposition, not a throughput result
The October 2023 partnership announcement aims to drive awareness of USDC remittances through educational campaigns and community engagement in the Philippines. Its reference to 18 million Coins.ph users describes the platform audience, not people observed making USDC remittances. The release identifies an intended use case and distribution opportunity; it does not document a live corridor’s transaction count, all-in customer price or retention. Later program outcomes are not established by this source.
Interpretation. A partnership can be commercially meaningful before it produces an observable transaction series. The analytical error is upgrading that opportunity into an adoption result. For a GTM team, education reach and completed remittances belong in separate measurement stages. A campaign's audience should not be used as the denominator of actual payment usage.
DBS / OCBC / UOB: the deposit comparator
On 10 September 2026, DBS reported live domestic SGD interbank transactions with OCBC and UOB using tokenized deposits and Swift's ledger. The release's technical note distinguishes the ledger's orchestration role from final settlement through existing systems: obligations were recorded on the banks' own infrastructures, then matched and netted. This establishes a reported live transaction milestone, not general customer availability or a measured cost reduction.
Interpretation. Banks can pursue interoperable payment workflows using tokenized deposits rather than an open-market stablecoin. The disclosed architecture also makes the settlement boundary explicit. Shared-ledger coordination and final settlement are separate functions. An evaluation that treated the orchestration event as the entire customer payment would miss the very institutional connection that makes the arrangement work.
Circle / Grab: a boundary case in programmability
Circle's September 2023 release describes a Grab Web3 Wallet pilot using NFT vouchers for the SG Pitstop Pack in Singapore, connected to Project Orchid's purpose-bound-money exploration. It establishes a bounded consumer experience with programmable entitlements. It does not establish broad stablecoin merchant settlement or the economics of the separate Triple-A top-up arrangement.
Interpretation. Programmability can be valuable without being evidence about remittance efficiency. A voucher's successful redemption answers a question about conditional use or customer experience. A completed cross-border payment answers a question about delivery of money. Combining those outcomes under one adoption headline would obscure what was actually tested.
| Program | Token's role | Customer endpoint | Evidence in selected source |
|---|---|---|---|
| SCB / Lightnet | Inter-institution settlement | Local-currency transaction | Reported commercialization |
| Nium | Corporate funding input | Fiat payout network | Reported availability |
| Grab / Triple-A | Consumer wallet funding | SGD wallet use; bank settlement | Provider case study of use |
| Coins.ph / Circle | Proposed remittance medium | Intended recipient access | Awareness partnership |
| DBS / OCBC / UOB | Tokenized bank-deposit workflow | Interbank obligations and settlement | Reported live transactions |
| Circle / Grab | Programmable voucher | Redemption of a defined benefit | Bounded pilot |
The last two rows are comparators, not stablecoin deployments. The classifications do not measure product quality. In particular, an announcement about a product's availability and a case study of customer use provide different kinds of evidence, even when both are described publicly as launches.
Findings
The starting balance changes the value proposition
A firm holding USDC already faces a different choice from one holding only local-currency deposits. For the former, connecting existing balances to payout infrastructure may remove a manual conversion process. For the latter, buying and then selling a token can add steps. The relevant comparison is the full path from the customer's actual starting asset to the beneficiary's required endpoint, not a comparison of blockchain fees with the headline fee of a bank transfer.
This leads to a segmentation hypothesis: existing token holders, payment intermediaries and conventional corporate treasurers should be evaluated separately. Their willingness to adopt may depend on different avoided costs. The corpus supports distinguishing the workflows, but does not estimate willingness to pay or show that one segment is larger. Those questions require customer and transaction data.
Blockchain finality is one timestamp in a longer payment
A useful measurement sequence is customer instruction, funds accepted, conversion completed, blockchain transfer confirmed, local payout initiated and beneficiary funds available. Some programs will omit a step or execute several concurrently. The correct sequence should be reconstructed for the specific product, with a clear definition of what each timestamp means.
A provider can improve the blockchain leg while leaving another step unchanged. Conversely, a product can improve the customer experience by hiding the token mechanics inside a familiar application. Neither observation is inherently negative. The problem arises when the measured timestamp differs from the one implied by the customer promise. “Seconds” should identify whether it refers to token confirmation, account credit or usable beneficiary funds.
Prefunding can move rather than disappear
A reduction in balances held by one participant does not establish a reduction across the entire chain. A provider may supply liquidity, conversion inventory or a credit facility that makes the customer's experience appear just-in-time. That can be commercially valuable, but its price and risk belong in the comparison. The question is who carries the balance after the workflow changes.
The same reasoning applies to operating work. Wallet management may disappear from a client's interface because an intermediary performs it. That is a service, not proof that custody, reconciliation and exception handling have ceased to exist. A proposed integration should identify the accountable operator at each handoff and the commercial terms under which that operator absorbs the work.
A reachable audience is not observed payment demand
The corpus includes both operating claims and awareness-oriented partnerships. Those sources support different conclusions. A platform audience can indicate a distribution opportunity; a recorded payment establishes usage; repeat usage indicates something about retention; a controlled cost comparison addresses economics. None should be substituted for another because it produces a larger number.
For commercial research, this suggests a staged evidence model: reachable customers, eligible customers, activated users, completed payments and retained usage. The model is our proposed measurement discipline, not a conversion funnel observed in the reviewed programs. A credible expansion plan should state which stage its evidence reaches and what remains to be measured.
An illustrative economic test
A minimal comparison can be written per completed payment:
Net benefit = avoided transfer and FX cost + released-capital value − new conversion, network, operating and risk cost.
Released-capital value can be approximated as P × r × d / 365, where P is the average balance actually released for the payment, r is the annual financing rate and d is the number of days released. P need not equal the payment principal: buffers, netting and credit arrangements can change it. This simple expression omits compounding and should be replaced by a treasury model when funding patterns are material.
Consider an explicitly hypothetical USD 10,000 payment, a fully released balance of USD 10,000 and a 5% annual financing rate. Releasing that balance for two days is worth about USD 2.74, or 2.74 basis points of the payment. An incremental conversion and operating cost of 10 basis points would cost USD 10. On these assumptions, capital release alone would not cover the new cost; additional avoided costs would need to exceed about USD 7.26. These are arithmetic examples, not prices or savings measured in any case.
| Days released | Value on USD 10,000 at 5% annually | Equivalent payment basis points |
|---|---|---|
| 1 | USD 1.37 | 1.37 bps |
| 2 | USD 2.74 | 2.74 bps |
| 5 | USD 6.85 | 6.85 bps |
| 10 | USD 13.70 | 13.70 bps |
The model shows why a universal savings claim is weak. Benefits can be substantial where several days of funding and expensive intermediate conversions are genuinely avoided. They can be negligible where funds were already available cheaply and the new route introduces extra conversion. Failed payments, manual reviews and unrecovered transfers should be measured over all attempted payments, then allocated consistently to completed payments; otherwise the comparison rewards a route for excluding its difficult cases.
Implications and tests that could change the conclusion
For a business-development team, the strongest initial proposition is a named customer workflow with an identifiable counterpart. A stablecoin funding product might target a platform already receiving tokens. A settlement integration might target a payment provider with a documented prefunding burden. An interbank workflow might target the banks and infrastructure connecting their deposit systems. These are hypotheses about fit derived from the classification, not evidence that the named firms are seeking new vendors.
The next step should be a bounded comparison against the customer's actual alternative. Record corridor, currencies, amount bands, business hours, starting balance, beneficiary availability, total fees, FX spread and manual interventions. Include ordinary and exception transactions. Compare equivalent endpoints, rather than a blockchain transfer on one side with a fully serviced bank payment on the other. Current permissions and service availability need product-specific verification before a live implementation; a historical launch does not answer those questions.
For a team entering Korea, one more boundary applies: the won leg. Edaily reported on July 21, 2026 that ten digital asset and stablecoin bills were pending in the National Assembly, and quoted an FSC official saying the commission would wrap up stablecoin legislation as soon as possible. The FSC’s September 4, 2026 tokenization roadmap places “an on-chain payments infrastructure linked to stablecoins” in its final phase, with timing tied to “the pending legislation on stablecoin.” A Korean proposal built on a won stablecoin therefore rests on a statute that did not exist at our cut-off. One built on a partner’s existing balance and a named bank or payout counterpart does not. Our August paper on the stalled Digital Asset Basic Act explains why that statute keeps slipping. Whether a given flow is permitted in Korea is a question for Korean counsel.
Our interpretation would weaken if token position in the workflow did not predict any material difference in integration requirements, counterparties or customer economics. It would strengthen if matched customer pilots showed distinct benefits for existing token holders, intermediaries and corporate treasury users after controlling for corridor and transaction characteristics. Neither test has been performed here. The classifications identify the comparisons that would make a later empirical study useful.
Conclusion
The central conclusion is that the token's role should determine the commercial analysis. Funding, inter-institution settlement, consumer acceptance, treasury deposits and programmable vouchers are different arrangements. A plausible business case identifies the beginning and end of the payment, the operator responsible for every transition, and the total cost of completing the customer outcome. That is the basis on which adoption claims can become testable business evidence.
Method and Limits
This paper is dated September 11, 2026 and uses material published on or before that date. It rests on 16 sources dated from September 2023 to September 10, 2026: Nium’s release, terms and product page, and its release with Visa on BLOOM; MAS’s BLOOM release; Triple-A’s Grab case study; releases by Circle, Coins.ph, and DBS, OCBC and UOB; the BIS Annual Economic Report chapter of June 2026; three press reports of SCB’s launch (The Block, Ledger Insights, Fintech News Singapore); Cointelegraph’s report of Circle’s 2024 fee change; and, for Korea, an Edaily report and an FSC release. The original review ran on September 11 and 12, 2026. Every figure was later re-checked against these sources.
The cases depend heavily on providers' own accounts. They are vulnerable to promotional selection, missing failures and inconsistent definitions of availability or volume. The undated Triple-A page is recorded as accessed on the review date; its current content must not be assigned an invented publication date. Older announcements are preserved as evidence of what was said then, not as exhaustive statements of the products' present status.
The sample is concentrated in Singapore-connected institutions and includes global networks. It cannot describe the entire Asian payments market, establish permission to operate in any jurisdiction, or quantify a regional addressable market. There are no interviews, confidential contracts, independently observed transfers or external peer review. The organizations cited are research subjects, with no implied relationship to or endorsement of ium Labs.
Two sources changed on re-check. SCB’s own release page could not be opened, so the SCB case rests on three press reports of it. Circle’s 2026 redemption tiers sit on a help page we could not open in a dated form, so the Circle figures here are from its 2024 fee change as reported; current terms need checking with Circle before any comparison. The Triple-A case study and Nium’s product page carry no date of their own.
The calculations are ium Labs scenarios: value in basis points = annual funding rate × calendar days saved ÷ 365 × released share × 10,000, rounded only for display. Uncertain at the cut-off: whether Nium’s product serves a given Asian corridor; the size of Grab’s top-up volume (the case study gives a growth rate, not a base); the commercial results of the SCB and BLOOM work; and whether and when Korea passes a stablecoin law. Nothing here is legal or investment advice.
References
[1]Nium. 2026-08-27. Nium launches USDC funding, letting businesses put stablecoin balances to work and free up trapped liquidity. nium.com.
[2]Nium. 2026-08-11. Pay In Service and Pay Out Service terms and conditions, section 6 (Stablecoin Pay In); last updated 11 August 2026. nium.com.
[3]Nium. Stablecoin payouts: product page and FAQ (undated). nium.com.
[4]Nium / Visa. 2026-08-25. Visa joins MAS-led BLOOM initiative with Nium as the first partner. nium.com.
[5]Monetary Authority of Singapore. 2025-10-16. MAS Launches BLOOM Initiative to Extend Settlement Capabilities. mas.gov.sg.
[6]Triple-A. Grab expands payment options with stablecoin top-ups, driving new user growth (case study, undated). triple-a.io.
[7]Circle. 2023-10-10. Coins.ph and Circle to Promote Financial Inclusion through Remittances in the Philippines. circle.com.
[8]Circle. 2023-09-14. Circle and Grab pilot Web3 experiences in Singapore. investor.circle.com.
[9]DBS, OCBC and UOB. 2026-09-10. DBS, OCBC and UOB complete first live blockchain-enabled SGD transactions on Swift’s ledger (including Note to Editors). dbs.com.
[10]Bank for International Settlements. 2026-06-28. Annual Economic Report 2026, chapter III: Anchoring trust in money: innovation beyond stablecoins. bis.org.
[11]The Block. 2024-10-17. Thailand’s Siam Commercial Bank introduces stablecoin service for international payments. theblock.co.
[12]Ledger Insights. 2024-10-17. Siam Commercial Bank launches stablecoin cross border payments. ledgerinsights.com.
[13]Fintech News Singapore. 2024-10-17. SCB Emerges as First Thai Bank to Adopt Stablecoins for Cross-Border Payments. fintechnews.sg.
[14]Cointelegraph. 2024-10-29. Circle raises USDC cash-out fees, affecting large-scale redemptions. cointelegraph.com.
[15]Edaily. 2026-07-21. 금융위 "스테이블코인 조속 입법…AI 커머스 신중 검토"(종합) (remarks by Yoo Young-joon, FSC Director General for Digital Finance Policy). edaily.co.kr.
[16]Financial Services Commission (Korea). 2026-09-04. FSC Introduces Policy Roadmap on Digital Transformation and Tokenization of Securities Issuance and Circulation. fsc.go.kr.